
This article provides a snapshot of country valuations for DM.
Many of the cheaper countries are located in Europe, where political risk has suppressed valuations, and the selloff has been more pronounced.
It goes to show there are still pockets of relative value across the globe.
With the correction in global stock markets still running its course, it's worth surveying some valuation statistics across Developed Market equities. Indeed, the current correction could easily go further, purely on sentiment and in the process cheapen valuations across the board. But in the meantime, this article takes a snapshot of the bottom end of DM equity valuations.
The table below comes from a broader discussion on Developed Market Equity Valuations in the latest Weekly Macro Themes report.
The table below shows the lay of the land in the bottom 10 ranked countries within DM.
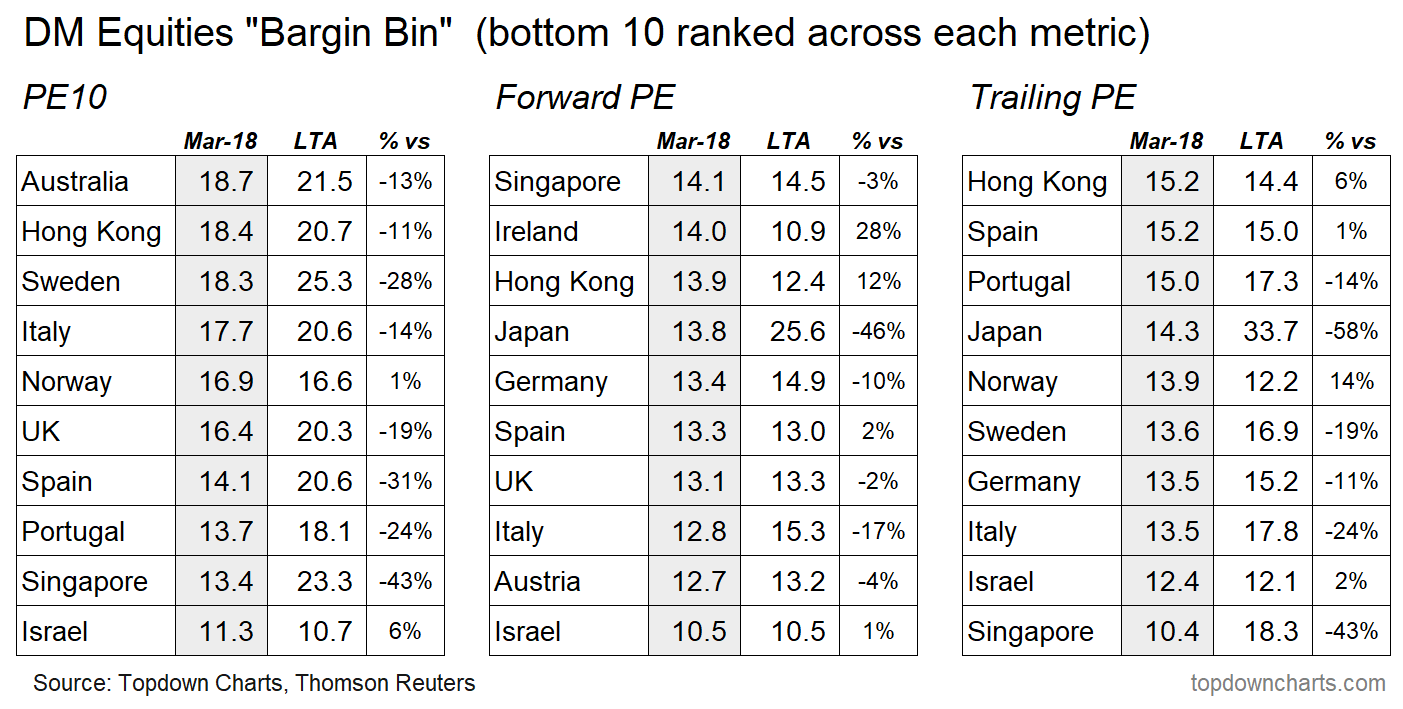
The table looks specifically at 3 different versions of the PE (price/earnings) ratio - a key equity market valuation indicator. First is the PE10 (price divided by 10-year average earnings), then the Forward PE (price divided by consensus next 12-month earnings from the Thomson Reuters I/B/E/S dataset), and the Trailing PE (price divided by the last 12 months' earnings). Each reading is shown next to its longest available historical average, and the final column shows the percentage premium/discount vs. long-term average.
There are some slight differences across the tables as each indicator gives a slightly different signal, yet the common mentions on the bottom half of the table are: Israel, Singapore, Italy, the UK, Germany, Portugal, Spain.
Notably, a number of those on the bottom end of the valuation rankings are European countries, and this makes some sense as I previously noted how European countries are among the culprits responsible for the weaker global equity breadth stats.


No comments:
Post a Comment